
GTrade
Case Study
Automated Trading Agent for Solana DLMM Pools
Overview
GTrade is an automated trading agent for Solana DLMM (Dynamic Liquidity Market Maker) pools. It was built to test whether a systematic, rules-based LP strategy could generate consistent yield from fee collection.
The project was not profitable financially — but it generated deep insights, reusable infrastructure, and a robust backtesting framework.
Backtest Results
Quantitative analysis · 500 candles · Dec 2024 – May 2026
30% Exit · 168h
Exit threshold · Re-enter delay
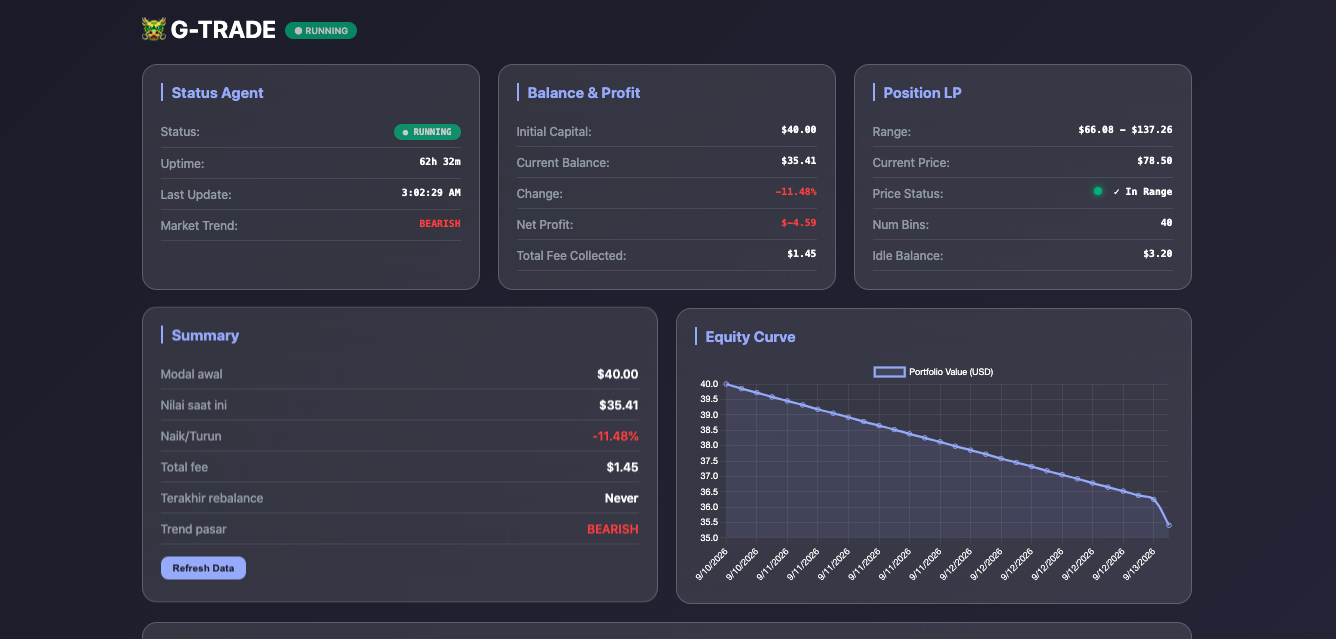
-11.47%
vs HOLD -46.68% → +35.21% better
6
+ 6 re-enters | 12 total txs
$1.80
$0.15 per transaction (realistic)
Strategy Comparison
All strategies · Parameter comparison
| Strategy | Exit | Delay | LP Return | Exits | Gas |
|---|---|---|---|---|---|
| G (30/168) | 30% | 168h | -11.47% | 6 | $1.80 |
| H (35/168) | 35% | 168h | -14.12% | 5 | $1.65 |
| D (30/240) | 30% | 240h | -17.43% | 6 | $1.80 |
| C (25/168) | 25% | 168h | -25.29% | 8 | $2.55 |
| No Exit (Active Range) | — | — | -22.77% | 0 | $0.75 |
| Adaptive | dynamic | dynamic | -21.25% | 9 | $1.80 |
| B (20/120) | 20% | 120h | -35.93% | 14 | $4.35 |
| A (15/72) | 15% | 72h | -45.96% | 19 | $5.85 |
Key Takeaways
Exit strategy > No exit — 30/168 outperforms active range by +11.3%
30% threshold · 168h delay adalah parameter optimal untuk periode ini
No absolute profit — semua strategi negatif di bear market SOL $261 → $78
SOL/USDC DLMM bukan untuk absolute return — lebih cocok untuk DCA
Framework siap untuk pool alternatif — USDC/USDT · SOL/JitoSOL
Problem
- DLMM is "short volatility"When price rises, the LP automatically sells. When price falls, the LP automatically buys. You are always on the wrong side of the trade — by design.
- Impermanent Loss (IL)IL is the opportunity cost compared to simply holding the asset. Without measuring it, you are blind to the real loss — and the fees you collect may not be enough to cover it.
- Parameter TuningExit threshold, re-enter delay, range width — every parameter affects the outcome. Finding the right combination requires systematic testing, not guesswork.
- Small Capital, High StakesWith only $20 in capital, one mistake can wipe out the entire fund. Risk management is not optional — it is the foundation.
Solution — System Architecture
Silogisme-Based Logic
Profit comes from fee, not price speculation. Consistency > quick multiplication. IL is the price you pay.
Parameter Testing
Exit threshold: 15%-40%. Re-enter delay: 72h-240h. Adaptive vs static strategy.
Risk Management
30% stop loss. Circuit breaker: 3 consecutive RPC errors → pause. Multi-RPC verification.
Telegram Integration
Real-time monitoring via Telegram bot. Commands: /status, /panic, /help. Daily reports at 20:00.
My Role
As Technical Project Lead & AI Orchestrator, I:
- Designed system architecture and trading logic
- Built the entire engine (17 modules) with AI as a development team
- Directed 4 AI models (DeepSeek, Claude, Gemini, Kimi) with specific roles
- Made the final decision to stop live trading when results showed no path to profitability
- Documented everything: blueprint, silogisme, lessons learned
Tech Stack
AI Orchestration
This project was developed using AI-as-Engineer approach.
DeepSeek
Lead Tech Architect, Strategic Decision Making
Claude
DeFi Expert, Brutal Honesty Analysis
Gemini
Strategy Consultant, Alternative Perspective
Kimi
DLMM Specialist, Technical Deep Dive
My Role: Problem framing & hypothesis design. Directing AI models toward specific outputs. Validating, rejecting, and integrating AI-generated code. Maintaining architectural consistency across 17 modules. Final decision making — including knowing when to stop.
Key Principle: AI generates. Human orchestrates.
Outcome
- ✅ Best Strategy: Static 30% exit + 168h re-enter → -11.47%
- ✅ With Exit vs No Exit: +11.3% better
- ✅ Live Trading: Not executed — made risk-conscious decision to stop
- ✅ Reusable infrastructure: 17 modules, backtesting framework
- ✅ Documentation: Blueprint + Silogisme + Lessons Learned
This is one approach — there may be better strategies out there that I haven't explored yet. The framework is built to be extensible for future research.
Lessons Learned
DLMM SOL/USDC is not for absolute return
IL in bear market cannot be defeated by fees alone. Parameter tuning won't find profit.
Exit strategy > no exit
With exit: -11.47%. Without exit: -22.77%. Difference: +11.3% better with exit.
Gas fee is not the bottleneck
Frequency of transactions matters more than gas optimization.
Backtesting methodology works
500 candles, exhaustive parameters, reproducible results.
Know when to stop
Not going live with suboptimal parameters is the right risk management decision.